
Term vs Spot Crude Contracts: How Gulf Producers Allocate Their Barrels
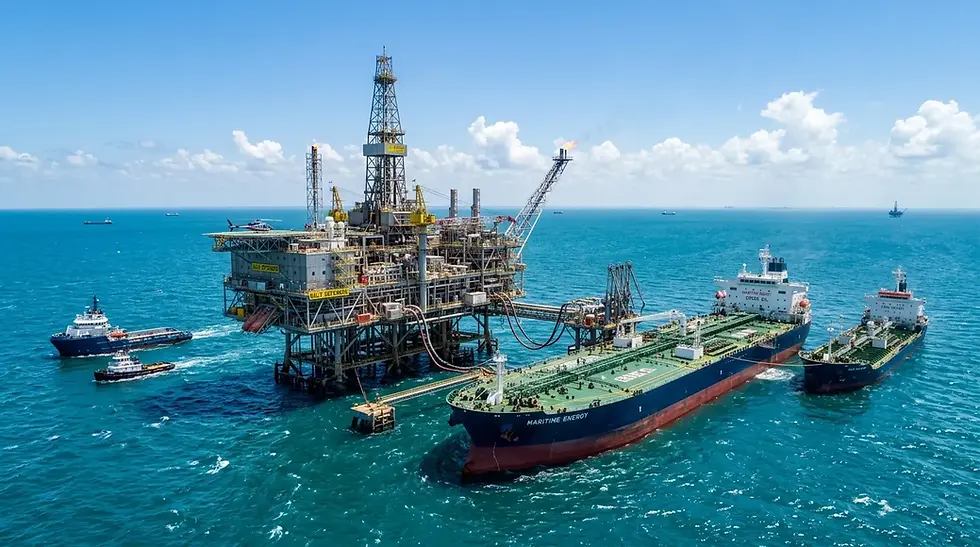
Crude allocation is a portfolio choice.
In the Arabian Gulf, producers balance term commitments, spot sales, benchmark formulas, and loading constraints to place each barrel where it best fits the commercial program.
For traders and procurement teams, the real question is not whether term is better than spot. It is how firm obligations, optional volumes, and pricing windows are sequenced so the export slate stays efficient and predictable.
What term and spot crude contracts mean
In physical oil trading, a physical oil cash market is the market where cargoes are traded for immediate delivery, while a futures contract is a standardized promise for delivery later. Term crude contracts are a different instrument from both. They are recurring commercial arrangements that define the grade, destination logic, nomination process, and pricing formula for a continuing supply relationship.
That is why the term versus spot decision is not just about price. It is also about how much volume a producer wants to commit, how much flexibility it wants to keep, and how much operational certainty a refinery customer needs. In the Arabian Gulf, that balance is shaped by loading programs, shipping options, destination requirements, and the timing of each cargo.
How Gulf producers allocate barrels
Allocation usually follows a simple commercial hierarchy. Core term liftings are planned first, optional volumes are matched next, and any remaining barrels are pushed to the spot market if they fit the loading schedule and the available vessel plan.
Firm term commitments come first. Producers protect the barrels already sold under recurring agreements, because those cargoes anchor customer supply and operational planning.
Spot barrels fill the gaps. If a load window is open, or a customer needs a prompt cargo, the uncommitted barrel can be directed to the spot market.
Grade and destination matter. A barrel is not interchangeable with every other barrel, because sulfur, density, transport route, and refinery fit all shape what can be sold where.
Shipping and loading capacity set the pace. Even when barrels are available on paper, they still have to fit the terminal schedule, vessel compatibility, and documentary requirements.
Compliance is checked before execution. Counterparty, vessel, and documentation screening help ensure that a cargo can move without avoidable legal or operational friction.
At Nedjma, our NOOR-Trading division supports teams that need market intelligence, commercial structuring, and execution discipline around this kind of allocation.
Term versus spot at a glance
Benchmark pricing is the backbone of this structure. EIA explains that benchmark crudes make it easier to price different grades and that differentials account for quality, transport, and regional supply and demand conditions. In the Gulf, reference benchmarks such as Dubai and Oman are therefore central to how export barrels are priced and allocated. Benchmark pricing in crude oil is less about headlines and more about commercial plumbing.
Key commercial differences
Factor | Term contract barrels | Spot cargoes | Allocation effect |
|---|---|---|---|
Delivery timing | Recurring liftings within an agreed program. | Prompt cargoes sold for a specific loading window. | Term anchors the base slate, spot absorbs flexibility. |
Pricing logic | Formula pricing tied to a benchmark and differential. | Price set very close to trade execution or prompt delivery. | Term tends to be more structured, spot more immediate. |
Volume certainty | Higher visibility for producer and buyer. | Lower visibility until the cargo is fixed. | Term supports refinery planning and producer cash flow discipline. |
Commercial role | Relationship supply for core customers. | Balancing supply for remaining barrels. | Spot clears what term programs do not fully absorb. |
Operational risk | Lower volume uncertainty, but still exposed to formula movement. | Higher exposure to prompt market conditions. | The chosen mix reflects each side's risk appetite. |
Why retrospective pricing is common on term contracts
EIA's petroleum marketing notes show that crude cargoes can be priced at loading or at landing, and that prices can be tied to spot or futures market levels. That means the final invoice may be fixed after the cargo has already been scheduled, moved, or even received. In practice, this is why many term contracts use retrospective pricing logic: the commercial relationship is agreed in advance, but the exact price is resolved against a later benchmark window.
Gulf national oil companies typically publish monthly official selling prices (OSPs) for each grade, expressed as a differential to a regional benchmark, and term buyers pay that formula rather than negotiating each cargo. This approach is useful because it keeps the price linked to the market reality of the cargo rather than to the day the contract was signed. It also lets the seller preserve a stable customer relationship while still using a benchmark differential that reflects crude quality, destination, and regional market conditions. For that reason, term barrels are managed through formula discipline, not through single-day price judgement.
For adjacent market structure and execution topics, the blog covers related trading and operational themes that help teams think beyond a single cargo.
How loading date changes the allocation decision
Loading date is the hinge between paper allocation and physical execution. EIA notes that acquisition can be recorded in the month of loading, the month of landing, or somewhere between the two, and that price determination can happen at loading or landing. In practical terms, a single slot shift can move a cargo into a different pricing window, a different vessel plan, or a different sales channel.
If a term customer lifts on schedule, the barrel stays inside the planned program.
If a term cargo slips, the producer may need to rebook the slot, adjust the formula timing, or move the barrel into the spot market if a buyer is available.
If a spot opportunity emerges, the seller can use an open loading window to place an uncommitted barrel quickly.
This is why loading discipline matters so much in the Arabian Gulf. The commercial decision is not made only on the trading screen. It is also made in the terminal schedule, the voyage plan, and the sequence in which barrels are nominated.
What procurement and trading teams should watch
Allocation is easier to manage when the commercial team reads the same signals as the operations team. The most useful questions are often simple: which barrels are already committed, which benchmarks govern the contract, how much loading flexibility exists, and how quickly can an optional cargo be reallocated if the plan changes?
Check whether the term program already covers the refinery's core intake.
Confirm the benchmark and differential that govern the cargo price.
Match the loading window to terminal capacity and vessel readiness.
Verify that title transfer, documentation, and screening steps are aligned before execution.
Keep a clear distinction between pricing risk, logistics risk, and counterparty risk.
In other words, the best allocation programs are not only commercial. They are also operational, documentary, and disciplined.
FAQ
What is the difference between term and spot crude contracts?
Term crude contracts are recurring supply arrangements that fix the grade, nomination process, and pricing formula for a continuing customer relationship, while spot cargoes are sold one at a time for a specific prompt loading window. Term barrels anchor the export slate and give both sides volume visibility, while spot barrels provide commercial flexibility at prices set close to the trade.
How do Gulf producers allocate barrels between term contracts and the spot market?
They usually start with committed term liftings, because those barrels already belong to a planned supply program. After that, they look at the remaining open slots, the quality of the crude, the destination requirements, and the vessel plan. If a cargo can be lifted without disturbing the base program, it can be sold on the spot market. If not, it stays inside the term framework. The allocation process is therefore a mix of commercial priority and physical feasibility, not a one-size-fits-all rule.
Why do Middle East oil exporters use retrospective pricing on term contracts?
Retrospective pricing helps align the final cargo price with the market conditions that exist around loading, landing, or the agreed pricing window. That matters because the value of a crude barrel depends on benchmark movements, quality differentials, and destination factors that may change after the contract is signed. For exporters, the method supports long term customer relationships without freezing the price too early. For buyers, it keeps the cargo linked to a recognized market reference rather than an arbitrary fixed number.
What percentage of Gulf crude is sold on term contracts versus the spot market?
There is no single public percentage that applies across all Gulf crude. The mix changes by producer, grade, destination, and month. What matters operationally is that term programs usually cover the core committed barrels, while the spot market takes the balancing volume. For a trading or procurement team, the better measure is not a headline share but the ratio between committed liftings, optional barrels, and the prompt cargoes that remain after nominations are fixed. That is the figure that drives allocation decisions.
How does the loading date affect term versus spot allocation for Gulf crude?
Loading date is often the practical trigger that decides whether a barrel stays inside a term program or becomes available for spot sale. If a cargo loads on time, it remains aligned with the original nomination and pricing window. If the slot slips, the seller may have to reprice the cargo, rebook the vessel, or move the barrel to another buyer. Because of that, loading date affects both logistics and price settlement. It is a small operational detail with a large commercial impact.
What should you do next?
If you are reviewing contract allocation, pricing logic, or loading discipline, start with the home page or contact the Nedjma team to discuss your needs.


